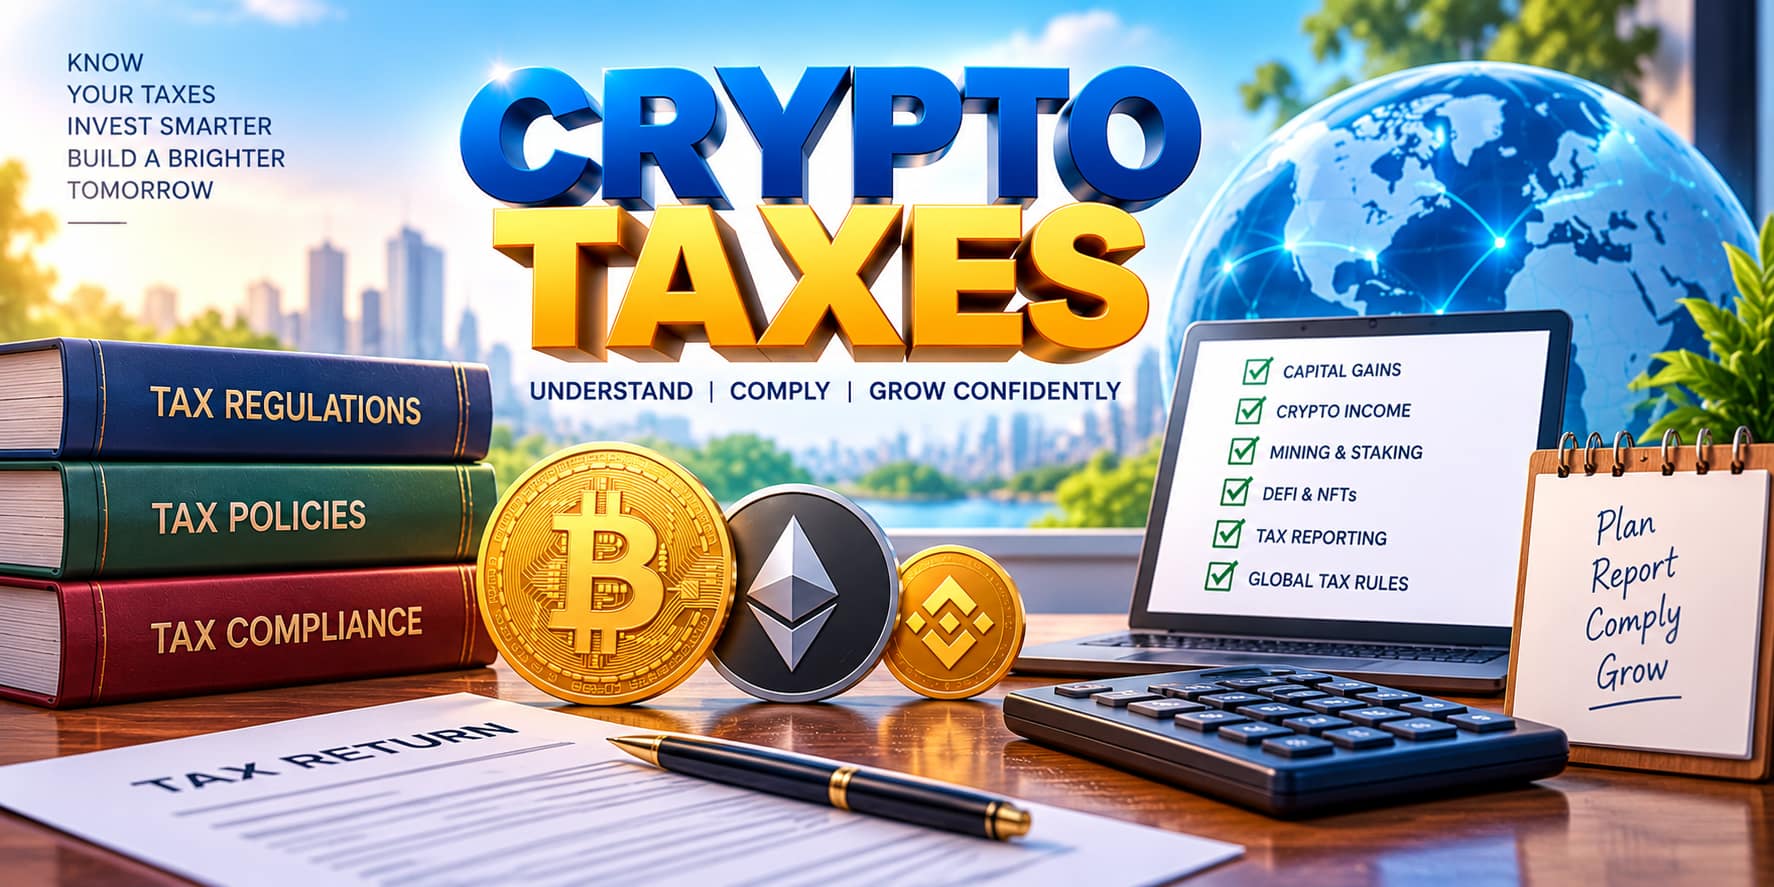
Crypto Taxes are the tax rules that apply to cryptocurrency and other digital-asset activities. Depending on where a person lives and how their local tax laws classify crypto, taxes may apply to profits from selling or exchanging digital assets, income received from certain crypto activities, or other taxable transactions.
There is no single global crypto tax system. Each country can determine how cryptocurrencies are classified, which transactions are taxable, how gains or income are calculated, and what records taxpayers must keep. This makes understanding the rules of your own tax jurisdiction essential.
Why Crypto Taxes Matter
Crypto transactions can create tax obligations even when the activity does not look like a traditional investment sale.
Buying crypto and simply holding it may be treated differently from selling it, exchanging it for another crypto asset, receiving crypto as income, or using crypto to pay for goods or services. The tax treatment depends on the applicable local rules.
Understanding these differences can help users keep better records and avoid mistakes when preparing their tax returns.
Common Crypto Activities That May Have Tax Implications
Depending on the jurisdiction, tax rules may apply to activities such as:
- Selling cryptocurrency for fiat currency
- Exchanging one cryptocurrency for another
- Spending crypto on goods or services
- Receiving crypto as income
- Mining or staking rewards
- Airdrops and certain token distributions
- DeFi-related activities
- NFT transactions
- Crypto received through business or professional activities
The tax treatment of each activity can differ significantly between countries. Comparative legal research also shows different approaches to mining, staking, airdrops and hard forks across jurisdictions.
Crypto Capital Gains
In many tax systems, selling or disposing of an asset for more or less than its acquisition cost can create a capital gain or loss.
For crypto users, this can involve transactions such as selling Bitcoin for a national currency or exchanging one digital asset for another.
The calculation can depend on factors such as acquisition cost, disposal value, transaction fees, holding period and the tax rules used in the relevant jurisdiction.
Crypto Income
Crypto received through certain activities may be treated as income rather than simply an investment gain.
Mining rewards, staking rewards, payments received in cryptocurrency and some airdrops can potentially fall into this category, depending on local law and the circumstances of the transaction.
Because the classification can vary, users should check the rules that apply where they are tax resident.
Crypto-to-Crypto Transactions
A common misconception is that taxes only matter when crypto is converted into cash.
In some jurisdictions, exchanging one crypto asset for another can itself be a taxable event. For example, exchanging Bitcoin for Ether may require the user to calculate the relevant gain or loss even though no fiat currency was received.
This is one reason accurate transaction records are important.
DeFi, Staking and Other Crypto Activities
Decentralized finance and blockchain-based services can create more complicated tax questions.
Liquidity provision, staking, lending, token rewards and other activities may have different tax treatments depending on the jurisdiction and the exact nature of the transaction.
There is no universal rule that automatically applies to every DeFi or staking activity.
Crypto Losses
Crypto investments can produce losses as well as gains.
Some tax systems allow certain investment losses to offset gains or be carried forward under specific conditions. Other jurisdictions may apply different limitations.
Users should therefore understand the local rules before assuming that every crypto loss can automatically reduce taxable income.
Keeping Crypto Tax Records
Good recordkeeping is one of the most practical parts of crypto tax management.
Useful records can include:
- Date and time of each transaction
- Asset and quantity involved
- Purchase or acquisition value
- Sale or disposal value
- Transaction fees
- Wallet addresses
- Exchange records
- Staking, mining or reward information
- Relevant transaction history
Keeping records from the beginning is generally much easier than reconstructing years of transactions later.
Crypto Exchanges and Tax Reporting
Crypto exchanges can provide transaction histories, account statements and other information that may help users prepare their records.
However, an exchange’s transaction history may not always contain everything required for a particular tax calculation. Transfers between personal wallets, transactions across multiple platforms and on-chain activities may need to be tracked separately.
The OECD’s Crypto-Asset Reporting Framework (CARF) is designed to improve international tax transparency by requiring reporting and automatic exchange of certain crypto-asset information between participating jurisdictions.
Crypto Taxes and Global Tax Reporting
International crypto taxation is becoming increasingly connected to broader tax-information reporting systems.
CARF provides an international framework for collecting and exchanging relevant information on crypto-asset transactions, while the actual tax liability remains dependent on each jurisdiction’s domestic tax rules.
This means users should not assume that using an overseas exchange or a self-custody wallet automatically removes local tax responsibilities.
Why Crypto Tax Rules Keep Changing
The crypto industry continues to develop through new assets, financial products and blockchain-based services.
Tax authorities are therefore adapting existing rules and introducing new reporting frameworks. The OECD’s CARF implementation work is one example of how international tax authorities are increasing visibility into cross-border crypto activity.
For users, this means older crypto tax information may not always reflect current requirements.
What Crypto Users Should Check
Before filing taxes, users should understand:
- Their tax residency
- How their country classifies crypto
- Which transactions are taxable
- How gains and losses are calculated
- How crypto income is treated
- What records must be retained
- What reporting deadlines apply
- Whether specific crypto reporting requirements apply
For complicated transactions or significant holdings, professional tax advice may be appropriate.
What We Cover
Our Crypto Taxes category focuses on practical and educational information about:
- Global Crypto Tax Rules
- Country-Specific Crypto Taxes
- Crypto Capital Gains
- Crypto Income
- Mining & Staking Taxes
- Airdrop Taxation
- DeFi Taxation
- NFT Taxes
- Crypto Tax Reporting
- Crypto Tax Records
- International Crypto Tax Developments
- Crypto-Asset Reporting Frameworks
Disclaimer: This content is for educational purposes only and is not tax or legal advice. Crypto tax rules vary by jurisdiction and can change over time.